Increased Cost of Compliance (ICC) & the FEMA 50% Rule Explained
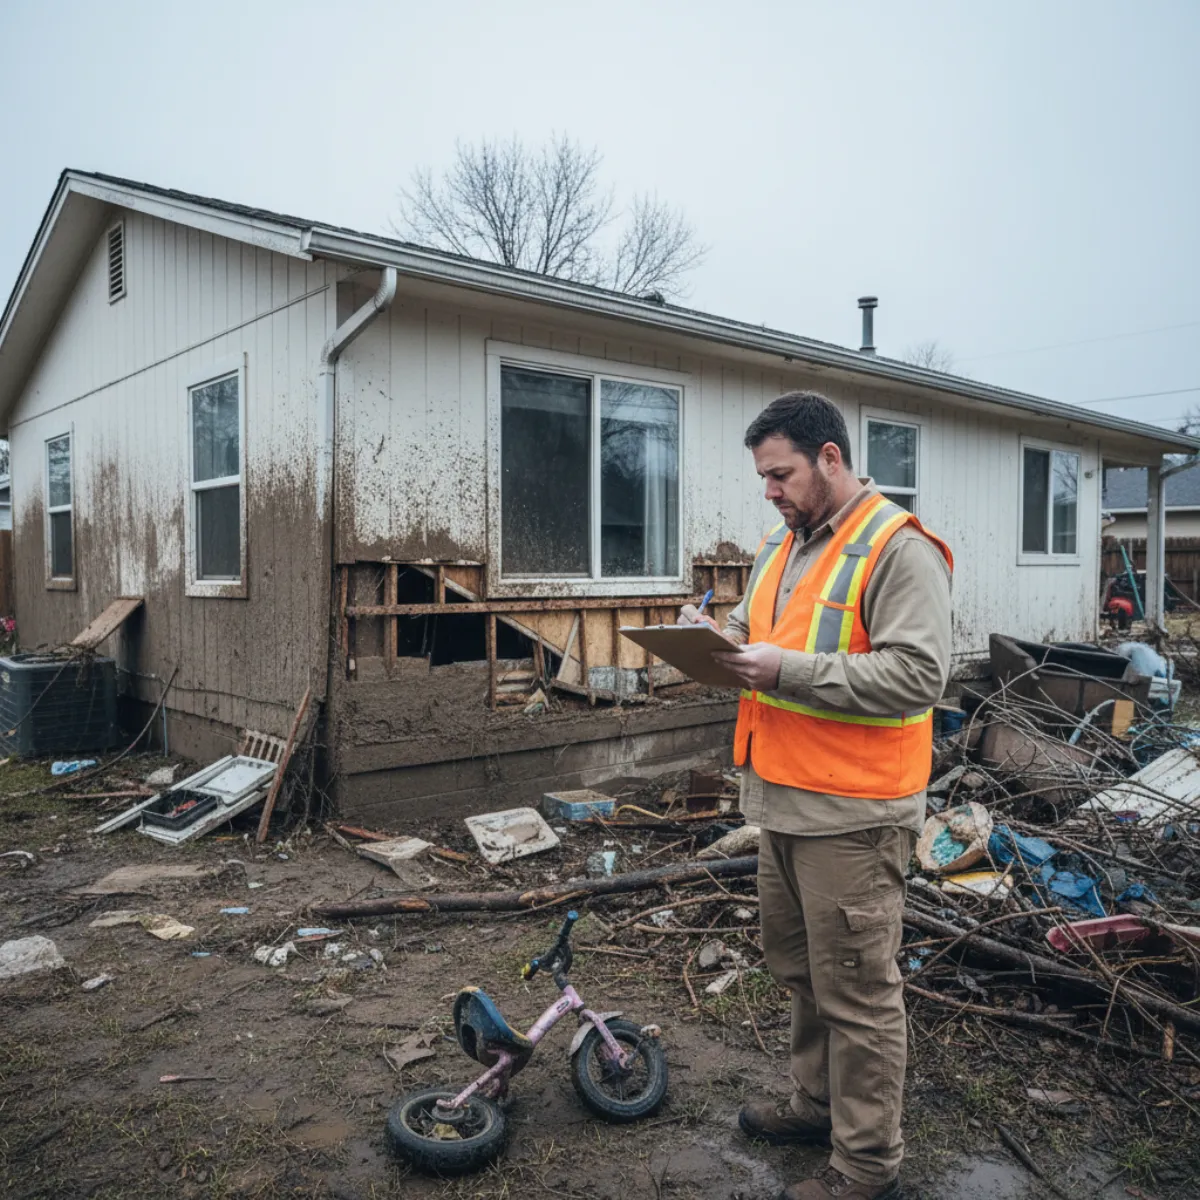
ICC on flood insurance is Increased Cost of Compliance coverage, included in most NFIP flood policies that carry building coverage. It pays up to $30,000, on top of your building claim, to bring a flood-damaged building up to current floodplain rules when your community declares it substantially damaged, meaning repairs equal or exceed 50% of its pre-damage market value.
FEMA lists four categories of compliance work that ICC can pay for:
- Elevation
- Relocation
- Demolition
- Floodproofing, for non-residential buildings and for homes whose basements meet FEMA's floodproofed-basement standard
ICC is one of the most valuable benefits in a flood policy, and one of the least understood, because it only activates under a specific official trigger. This guide explains what sets it off, what it pays for, and how the 50% rule works, so you know what to ask for if your home floods.
What is Increased Cost of Compliance coverage?
ICC is not a separate grant you apply for. It is Coverage D of the Standard Flood Insurance Policy, and the policy itself says it only applies to policies with building coverage. FEMA's Flood Insurance Manual (October 2025) lists where it is not available at all: contents-only policies, Dwelling Form policies on individual condominium units (the association's own policy carries it), Group Flood Insurance Policies, Emergency Program policies, and garages or carports. The policy form excludes garages outright, while the manual treats a detached garage insured under its own policy differently, so confirm with your insurer before counting on ICC for one.
When a covered building is declared substantially or repetitively damaged by flood, ICC provides up to $30,000 toward the cost of meeting your community's current floodplain requirements. That money comes on top of the claim payment for the flood damage itself, with one ceiling: the building claim and ICC together cannot exceed the NFIP maximum for the building, $250,000 for a home. FEMA's Claims Manual (June 2025) gives the example: a $250,000 policy that pays $240,000 on the damage leaves only $10,000 for ICC.
$30,000Maximum ICC payment toward compliance, on top of your building claim. For a home, the two together cannot exceed $250,000.
What is the FEMA 50 percent rule?
The 50% rule is the main trigger. If your community's floodplain administrator determines that the cost to repair flood damage equals or exceeds 50% of the building's market value before the flood, the building is "substantially damaged." That declaration does two things: it requires the rebuilt structure to comply with current floodplain rules, and, when the damage came from a flood and your policy has building coverage, it opens your ICC coverage.
| Trigger | Threshold |
|---|---|
| Substantial damage | Flood repair cost ≥ 50% of pre-damage market value |
| Repetitive (cumulative) damage | Flood damage twice in 10 years, repairs averaging ≥ 25% of market value each time, the earlier claim paid by the NFIP, and a cumulative-damage rule enforced by your community |
What does ICC cover?
ICC funds the measures that bring a structure into compliance:
- Elevation of the building above Base Flood Elevation. See cost to elevate a house.
- Relocation of the building to a lower-risk site.
- Demolition and clearing of the structure.
- Floodproofing of a non-residential building. The policy and FEMA's 2025 Claims Manual also allow ICC to floodproof a home's basement, but only one that meets FEMA's standard in 44 CFR 60.6, which applies in the 53 communities FEMA has granted a residential basement exception.
How ICC fits with FEMA grants
ICC and the FEMA mitigation grants can work together. ICC delivers up to $30,000 through your existing policy after a flood, while FMA and HMGP can cover a larger share of a bigger project like elevation. Combining the two can substantially reduce what you pay out of pocket. See FEMA flood mitigation grants for how the cost-share programs work, and use the Payback Estimator to flag ICC eligibility in your own scenario.
Frequently asked
What is Increased Cost of Compliance coverage?
What is the FEMA 50 percent rule?
What counts as substantial damage?
How much does ICC pay?
What does ICC cover?
Estimate your real number
Run your mitigation cost, current premium and flood-risk status through the Payback Estimator: net cost after grants, lower insurance, and the payback in years.